Western Digital Beats Forecasts as Revenue Jumps 55 Percent and Guidance Tops Estimates
The hard drive maker reported fiscal first quarter adjusted earnings of $4.64 a share on revenue of $4.38 billion, both well above Wall Street forecasts, and guided second quarter sales far above what analysts expected.
Key points
- Western Digital beat Wall Street forecasts by a wide margin on Thursday, as demand from data centers lifted the hard drive maker's fiscal first quarter revenue 55 percent from a year earlier.
- Profit rose faster than sales.
- Chief executive Irving Tan said the quarter showed strong demand and steady execution.
Western Digital beat Wall Street forecasts by a wide margin on Thursday, as demand from data centers lifted the hard drive maker's fiscal first quarter revenue 55 percent from a year earlier. The company reported revenue of $4.38 billion for the quarter ended Oct. 2, 2026, against analyst expectations of about $4.1 billion. Adjusted earnings came in at $4.64 a share, above the $4.11 a share analysts had expected and up 161 percent from a year earlier.
Margins widen as drive prices hold
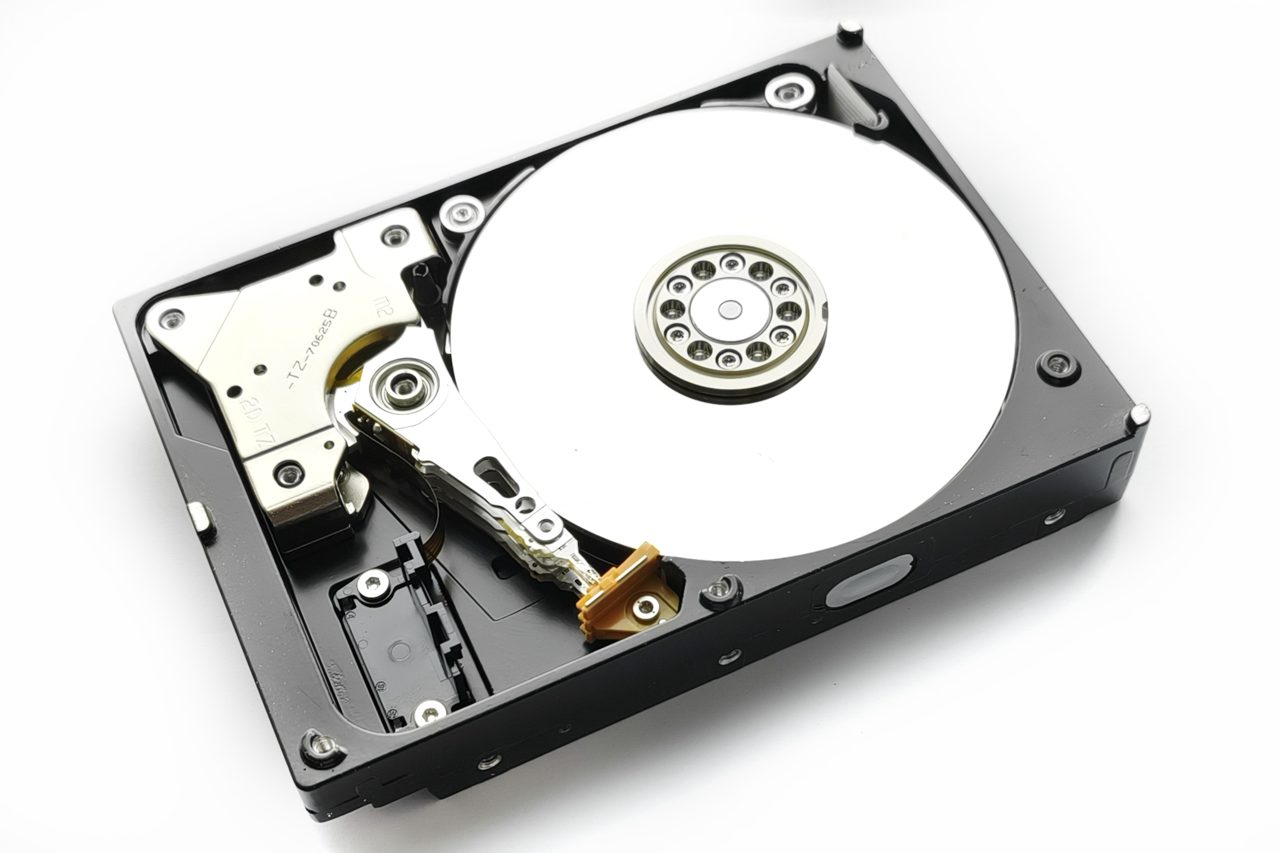
Profit rose faster than sales. The company's non-GAAP gross margin reached 58.1 percent, up from 54.4 percent in the previous quarter and 43.9 percent a year ago, and its non-GAAP operating margin reached 49.1 percent. The numbers show the pricing power Western Digital holds while cloud companies buy storage as fast as the industry can supply it. Western Digital and Seagate are the only two U.S. companies that produce hard disk drives, and data center operators still keep large volumes of AI data on drives because they cost less per unit of storage than flash memory.
Chief executive Irving Tan said the quarter showed strong demand and steady execution. "Fiscal 2027 is off to a strong start, with results exceeding expectations, driven by robust customer demand and disciplined execution," Tan said. The company raised its quarterly cash dividend by 17 percent to $0.175 a share.
Guidance far above forecasts
The outlook did more work than the quarter itself. For the fiscal second quarter, Western Digital expects revenue of $5.0 billion to $5.2 billion, well above the roughly $4.6 billion analysts had forecast. It expects adjusted earnings of $5.60 to $6.00 a share, against expectations near $4.84 a share, and a non-GAAP gross margin between 60 percent and 61 percent. A guide that far above the consensus tells investors the company sees data center orders holding at a high level into the end of the calendar year.
A hard session came first
The results landed after a rough day for the shares. Western Digital stock fell 6.4 percent in regular trading on Thursday, closing at $354.19, as the Nasdaq Composite dropped 2.6 percent and chip and AI linked stocks sold off on worries about the cost of the AI buildout. The stock is down 53 percent from its closing high on June 18. The hard drive business runs in cycles, and investors have been asking for steady proof that prices and margins can keep rising. Thursday's guidance gives them that proof for one more quarter. The next test is whether data center customers keep ordering at the pace the guide assumes.