Maruti Suzuki Q2 Profit Falls 26 Percent Despite Record Sales
Consolidated net profit fell 26.36 percent to Rs 2,466.1 crore in the July to September quarter, even as Maruti Suzuki sold a record 696,654 vehicles and sales rose 26.1 percent.
Key points
- Maruti Suzuki, India's top carmaker by sales, reported a sharp fall in profit for the July to September quarter on Tuesday, October 27, 2026, even as it sold more vehicles than in any previous…
- Revenue rose strongly on the record sales.
- The profit fall came from costs.
Maruti Suzuki, India's top carmaker by sales, reported a sharp fall in profit for the July to September quarter on Tuesday, October 27, 2026, even as it sold more vehicles than in any previous quarter. Consolidated net profit fell 26.36 percent year on year to Rs 2,466.1 crore, from Rs 3,349 crore a year earlier. Standalone profit was Rs 2,414.9 crore, below analysts' estimates of Rs 3,105 crore compiled by LSEG and reported by Reuters.
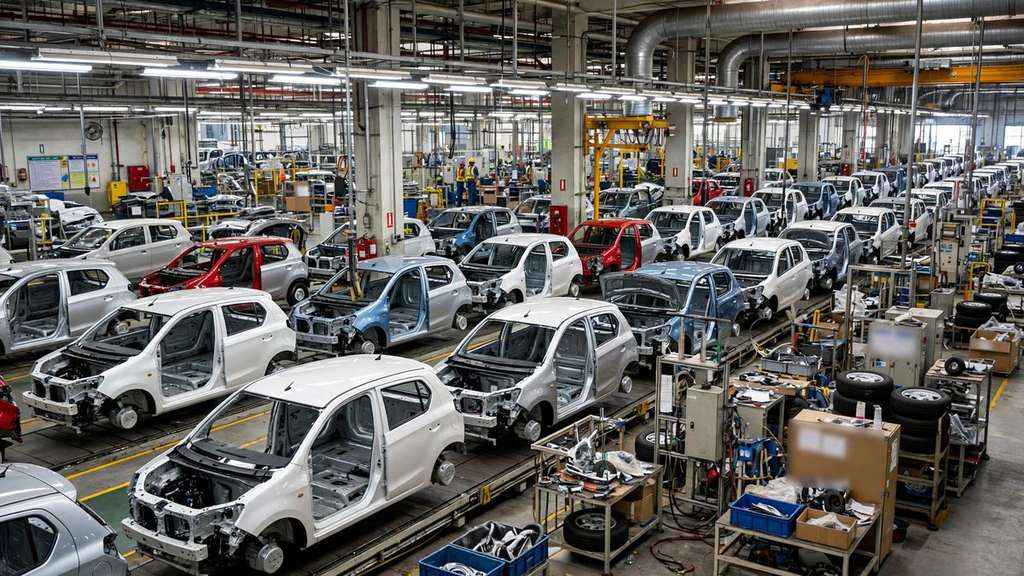
Revenue rose strongly on the record sales. Consolidated revenue from operations rose to Rs 53,355.5 crore from Rs 42,344.2 crore a year earlier, and net sales rose 26.1 percent to Rs 50,615.5 crore. The company sold a record 696,654 vehicles in the quarter, up 26.5 percent from 550,874 a year earlier. First half sales were the highest ever at 1,379,378 units, up 27.9 percent.
Costs rose faster than sales
The profit fall came from costs. Consolidated expenses jumped to Rs 50,619 crore from Rs 39,018.4 crore a year earlier, and the cost of materials consumed rose to Rs 37,488.5 crore from Rs 25,324.2 crore. Operating profit, measured as EBIT, fell 17.1 percent to Rs 2,803.7 crore from Rs 3,382 crore. The company blamed adverse commodity prices for steel and copper in the context of the West Asia conflict, adverse foreign exchange movement, and lower non operating income from mark to market losses on invested surplus.
Those pressures explain the gap between the sales record and the profit result. Higher material costs cut the margin on each vehicle, currency movement added to expenses, and weaker investment income removed a support that had helped profit in the earlier period.
Prices, share and orders
In September the company raised prices of select models by up to Rs 20,000, its third hike since May. Domestic market share rose 2.2 points to 40.8 percent. Network inventory sat at about 17 days, and pending bookings stood at about 200,000 units. Exports were 108,119 units, against 110,487 a year earlier, a small decline that contrasts with the strong domestic result.
What happens next depends on whether commodity and currency pressures ease and whether the price hikes hold without slowing orders. The booking backlog of about 200,000 units and the lean 17 days of inventory give the company a clear order book for the coming months, but the quarter shows that record volume alone does not protect profit when input costs rise this fast. Investors and dealers will watch the next quarter for signs that margins recover, because the company has already used three price hikes since May and still could not offset the rise in steel, copper and other material costs this quarter.